THE IUL FACTORY
Your Money Should Work as Hard as You Do.
You're earning six figures — but your savings account pays pennies, the market keeps you up at night, and taxes take a bigger bite every year. There's a way high earners put their extra cash to work: a cash value life insurance policy designed for growth potential, tax advantages, and access to your money when opportunity knocks.
Takes 60 seconds. No obligation. No pushy sales call.
Not everyone qualifies — take the 60-second quiz to see if you do.
THE WEALTH PARADOX
High Income. High Taxes. Low Options.
The traditional financial system was engineered to extract and lock away the wealth of top earners, keeping you reliant on rules you never wrote.
You're taxed at every turn.
Top tax brackets erode nearly half of every marginal dollar earned. Qualified accounts don't eliminate taxation - they merely defer it until rates inevitably rise.
Your cash sits still.
Treasury yields and high-yield savings accounts cannot outpace true inflation and asset price escalation. Storing liquidity in stagnant accounts quietly penalizes conservative capital.
Banks profit off your money - not you.
Institutions take your deposits, leverage them at 10x through fractional reserve lending, and capture the arbitrage while leaving you with taxable table scraps.
It's called being your own bank. And it starts with a properly structured cash value policy.
TAX ADVANTAGES & ASSET PRESERVATION
Keep More of What You Earn.
Cash value life insurance offers tax-deferred growth potential, an income-tax-free death benefit for your loved ones, and tax-advantaged access to your money through policy loans.
Tax rules are complex and change. Always confirm your situation with a qualified tax professional.
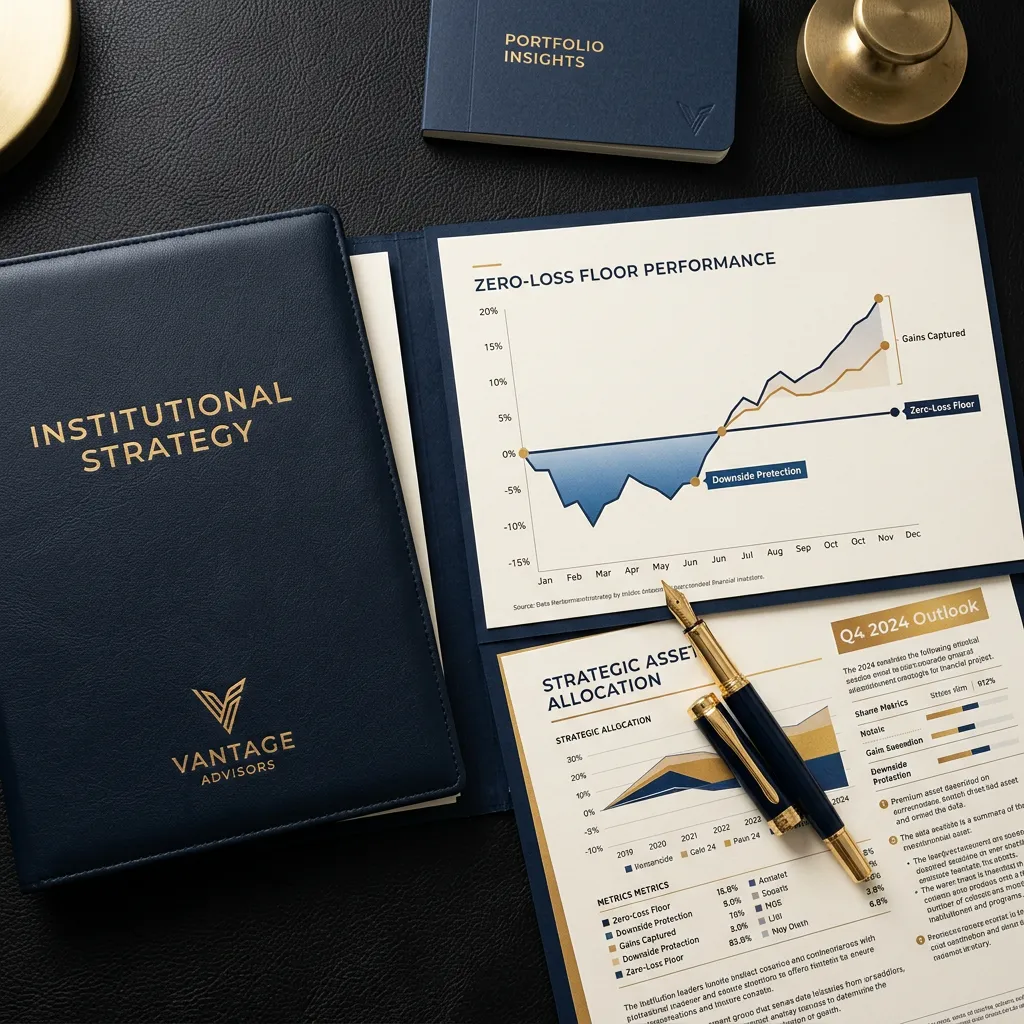
PRINCIPAL PROTECTION & 0% FLOOR
Growth Potential Without Riding the Roller Coaster.
When equity markets drop, your cash value is protected by a contractual 0% annual floor. Your interest crediting is tied to index benchmarks during up markets, but when the benchmark crashes, your baseline is locked in — you never lose accumulated gains or principal to market downturns.
- Guaranteed 0% contractual floor prevents negative market returns
- Annual reset locks in all credited gains so you never backslide
- Upside participation linked to major market indices without direct risk
Compliance Disclaimer: Guarantees are backed by the claims-paying ability of the issuing life insurance carrier. Policy loans and withdrawals may impact cash surrender value and death benefits. Tax rules are complex and subject to statutory change. Always confirm your specific circumstances with a licensed financial professional and tax advisor.
BENEFIT 03 : PRIVATE FINANCING
Be Your Own Bank.
Borrow against your own cash value - no bank application, no credit check, no approval process. You set the repayment terms. Your money keeps working while you use it.
Policy loans aren't free money - interest accrues, and unpaid loans reduce your death benefit and cash value.
TAX-ADVANTAGED WEALTH PRESERVATION
Leave More Than Memories.
Cash value life insurance offers tax-deferred growth potential, an income-tax-free death benefit for your loved ones, and tax-advantaged access to your money through policy loans.
- Income-tax-free wealth transfer directly to chosen beneficiaries
- Bypasses standard probate friction for swift estate settlement
- Preserves full intergenerational capital without liquidity haircuts
Tax rules are complex and change. Always confirm your situation with a qualified tax professional.
THE ONBOARDING BLUEPRINT
A Simple Path to Coverage
Three deliberate stages engineered to preserve your capital, maximize tax-free accumulation, and secure structured private liquidity.
01
Take the 60-second quiz
Answer a few brief strategic questions to evaluate your current income tier, retirement timeline, and potential for private arbitrage.
02
Connect with an executive wealth specialist to review personalized policy illustrations, stress-test historical yield models, and verify eligibility.
03
Get covered
Formalize your top-tier institutional contract, initialize your tax-sheltered banking reservoir, and establish multi-generational liquidity.
Confidential qualification • No impact to credit score
Did you know… you can roll over your 401(k) into an IUL?
Not everyone qualifies — take the 60-second quiz to see if you do.
EXECUTIVE LEADERSHIP & LICENSURE
Meet Your Strategists
Direct access to the co-owners of IUL Factory. Fiduciary precision, multi-carrier brokerage authority, and contract architectures designed for zero downside risk.
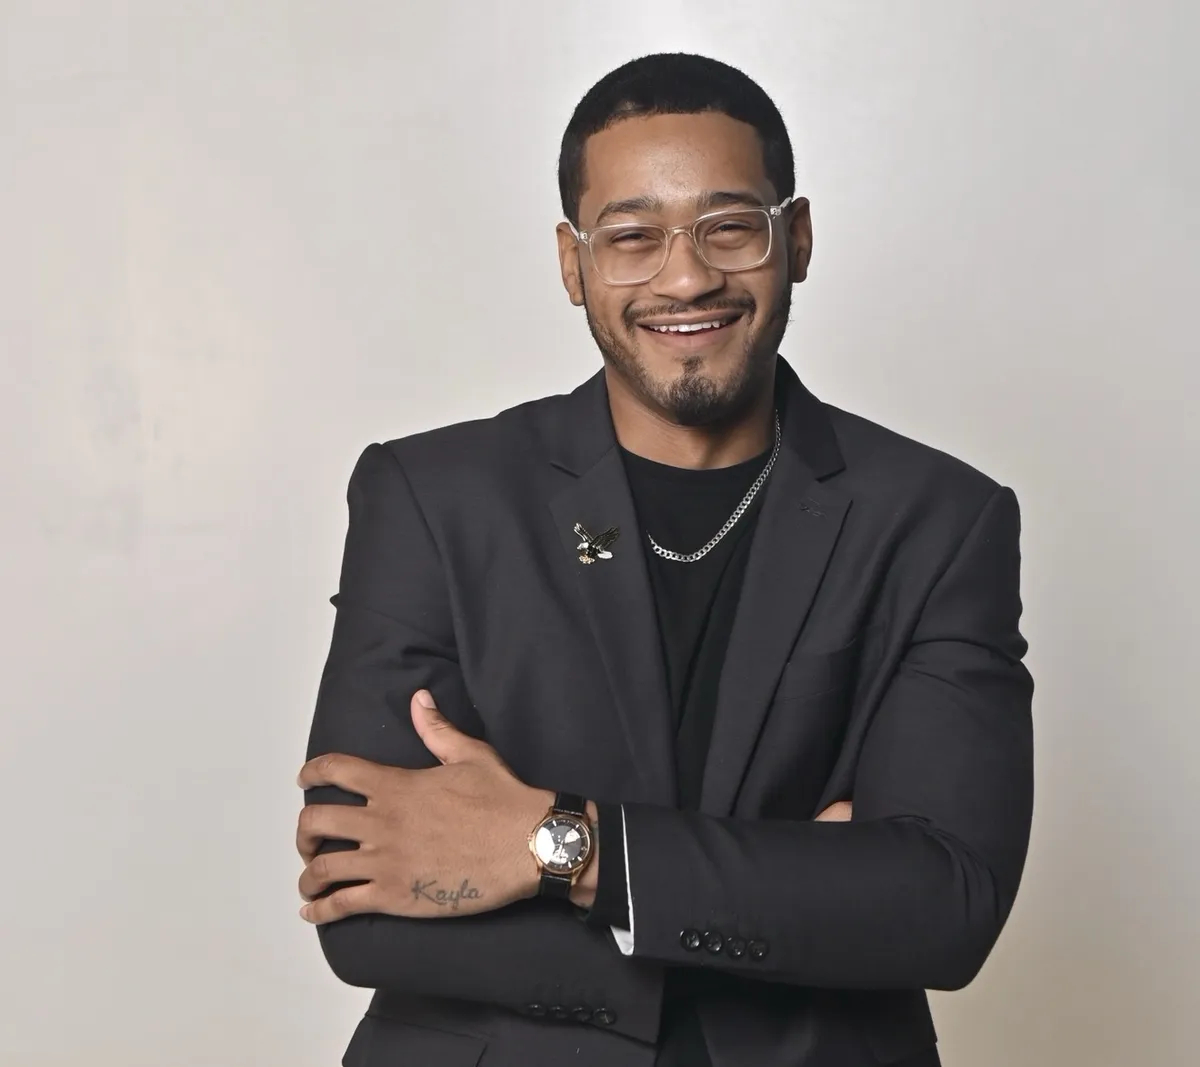
Michael Johnson III
CO-OWNER, IUL FACTORY
- Dedicated IUL contract specialist
- Licensed across 30 states nationwide
- National Producer Number: NPN 21384383
- Direct access to all A+ rated carriers
OBJECTIVE DILIGENCE & TRANSPARENCY
Clarity & Transparency
Sophisticated wealth strategies require unvarnished facts. We dispel the myths around policy performance, internal drag, and contract liquidity before any capital is committed. Review the essentials here, or explore a bespoke contract illustration tailored to your tax bracket during your one-on-one session.
Is this an investment?
No. An Indexed Universal Life (IUL) contract is legally permanent life insurance, not a direct security or mutual fund. Your cash value is never directly exposed to Wall Street equity markets. Instead, your annual yield is indexed to an underlying benchmark like the S&P 500 through contractual options, backed entirely by tier-1 institutional insurance reserves.
What happens if the market crashes?
Your principal and locked-in historical gains remain protected by a strict contractual 0% floor. If the market plunges 20%, 30%, or 40%, your credited index yield for that period is simply 0%. You absorb zero negative market volatility, preserving 100% of your accumulated asset base for the subsequent compound recovery.
How do policy loans work?
Instead of taxable withdrawals, you access capital through institutional policy loans collateralized by your death benefit. Because your underlying cash balance never exits the contract, 100% of your principal continues compounding uninterrupted. This enables positive interest arbitrage whenever credited index returns outpace the fixed loan rate.
Who is this for?
This specialized strategy is engineered for high-income professionals, real estate operators, and business owners who have phased out of Roth IRA eligibility, maxed qualified retirement limits, or seek an institutional-grade, creditor-protected asset reserve exempt from federal and state income taxation.
Are there fees?
Yes. Every insurance contract includes statutory costs, including premium loads, administrative fees, and cost of insurance (COI). We structure these policies using maximum early cash-accumulation architecture—reducing the death benefit to the legal IRS minimum—which drives the lion's share of every dollar straight into cash growth.
Is my money locked up?
No, but it is intentionally engineered as a medium-to-long-term wealth architecture. While early-year surrender values reflect contract setup charges, liquid cash value is accessible via policy loans starting in Year 1 without the IRS age-59½ early withdrawal penalty, mandatory distributions, or banking scrutiny.
EXCLUSIVE QUALIFICATION
Your Money Should Work as Hard as You Do.
Take 60 seconds. Find out if this strategy fits your situation. Free. No obligation.
Confidential Assessment • Direct Advisory Review • Zero Obligation
IUL Factory · Powered by Anchor Agencies. Licensed in 30 states. This page is educational and does not constitute financial, tax, or legal advice.
© 2026 IUL Factory. All rights reserved.